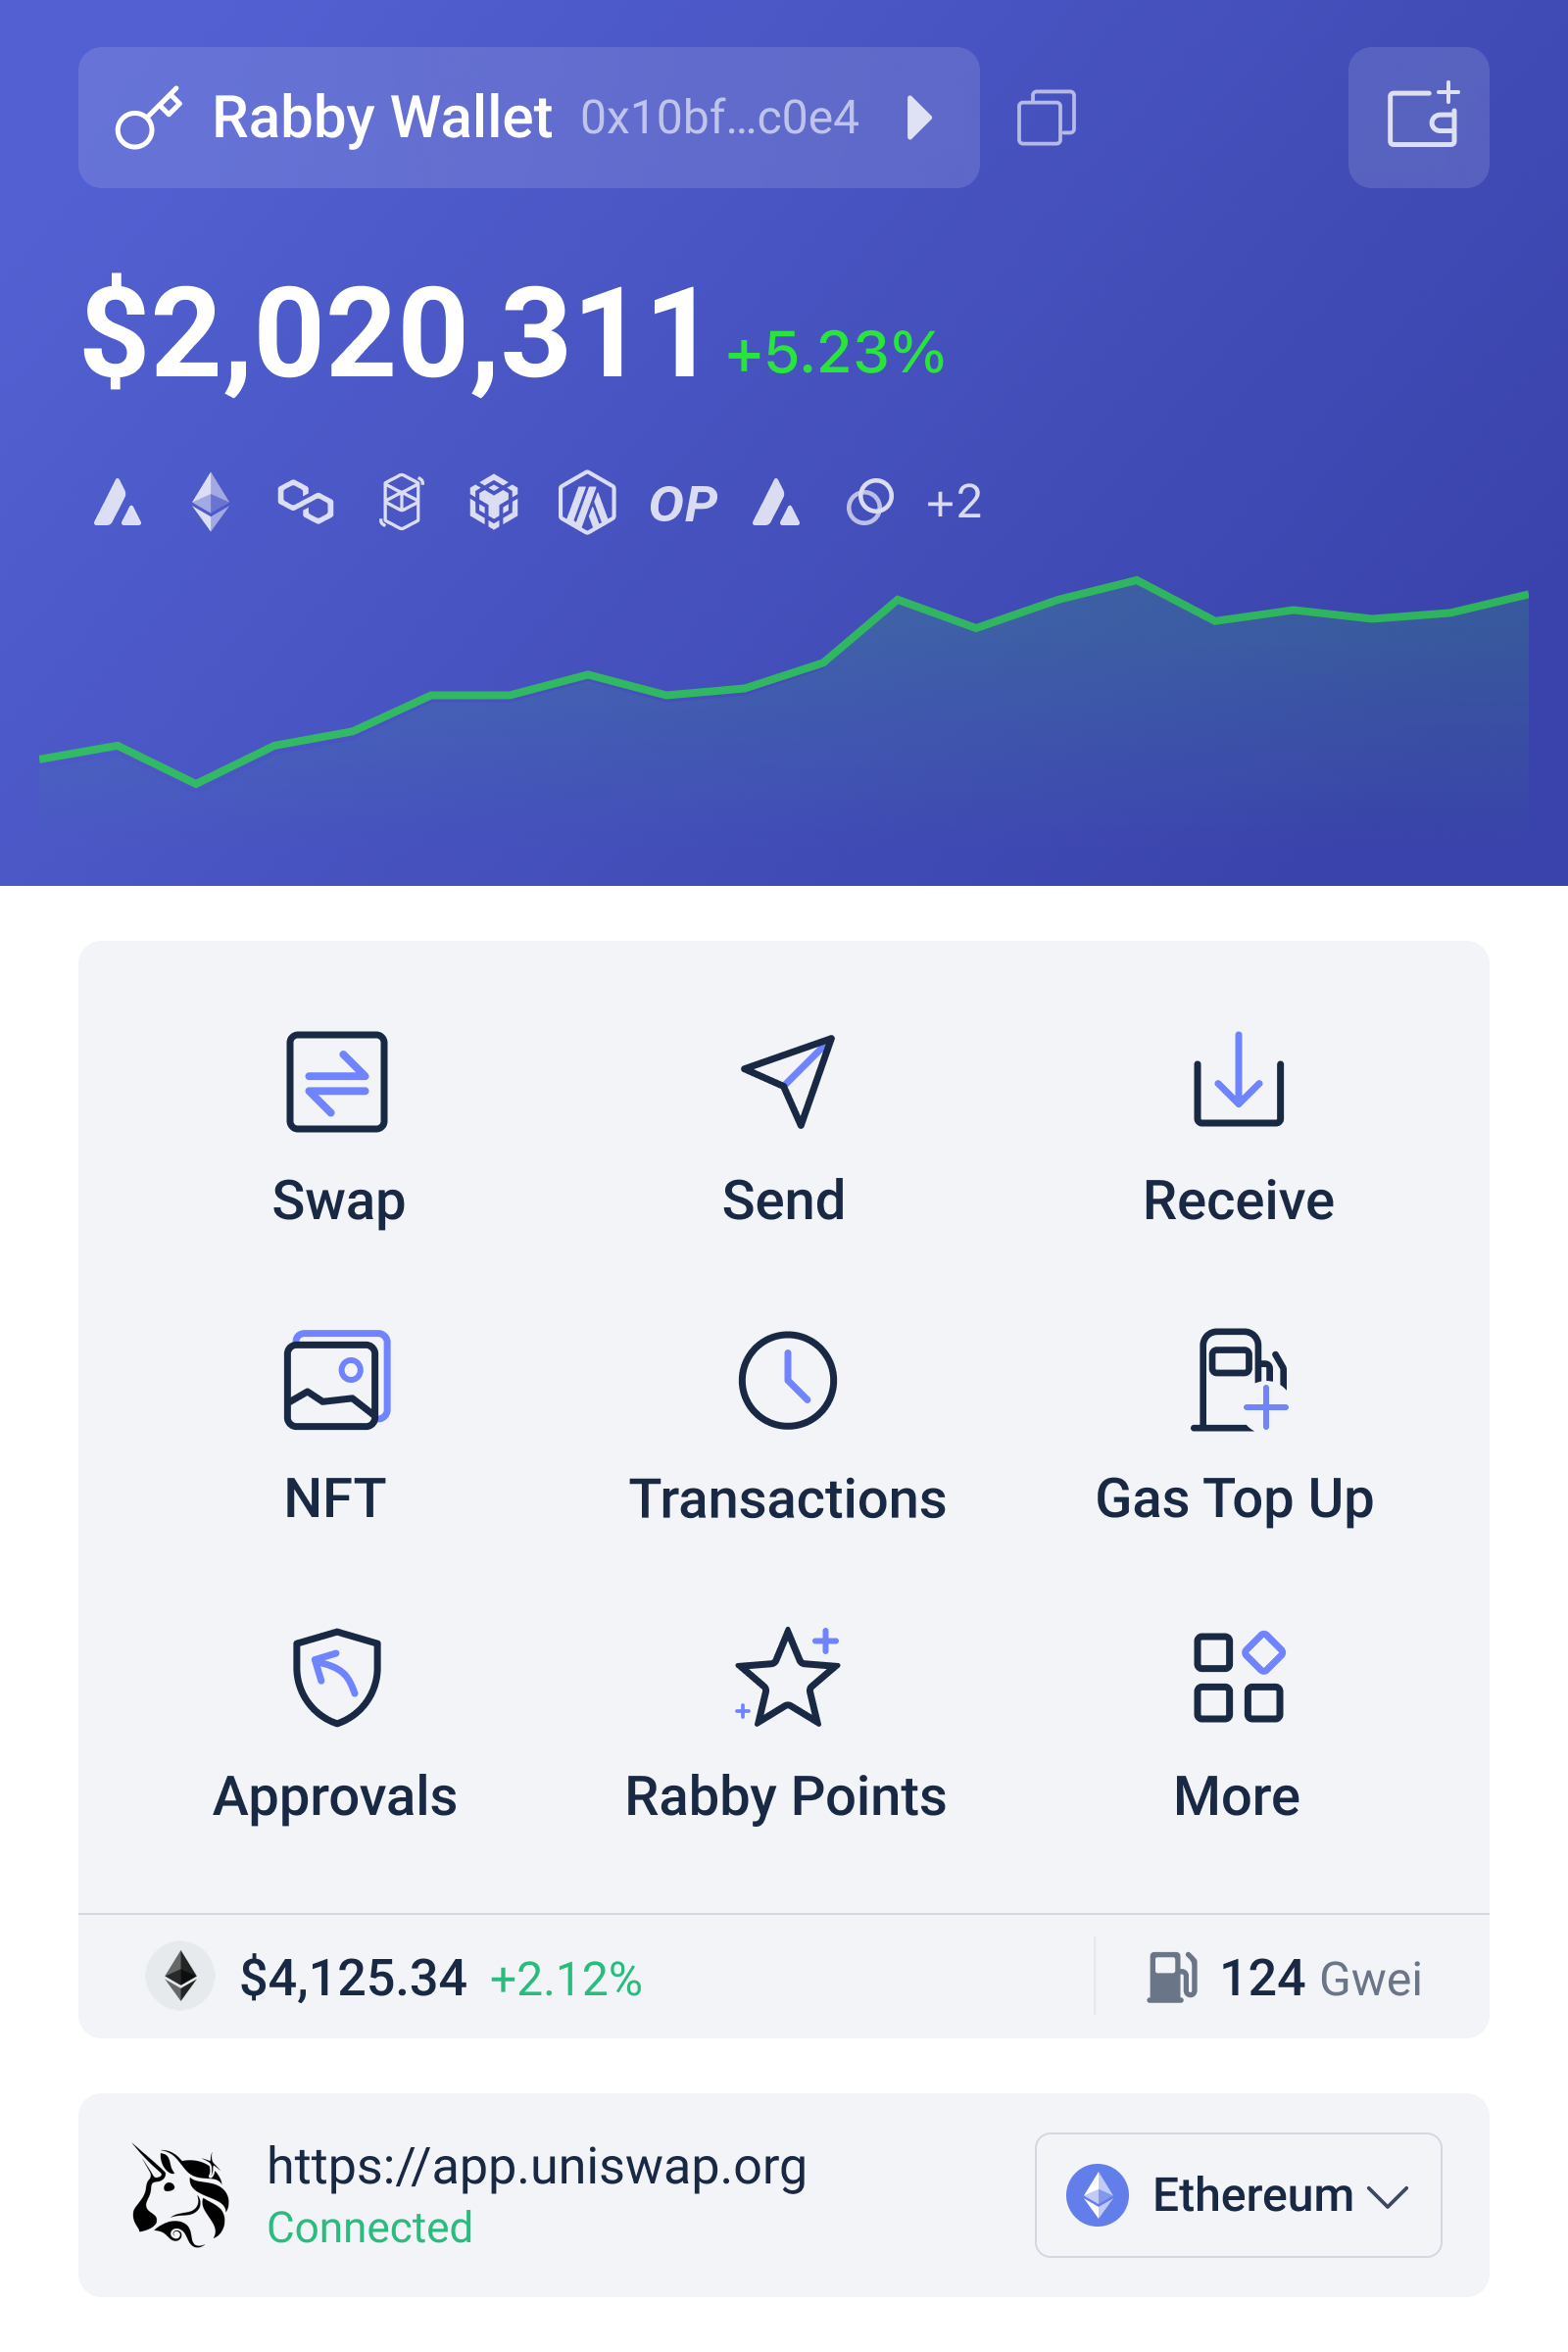
You open your wallet expecting a simple answer: how much do you own, and what will this transaction do? Instead, the screen shows assets spread across Ethereum, an Ethereum layer-2 network, and a smaller chain you used months ago. A swap appears to involve one token, several contract calls, and an approval you do not remember granting. The portfolio total looks plausible, but the risk is harder to see.
That situation exposes a common misconception in DeFi: portfolio tracking is treated as an accounting problem, while smart contract interaction is treated as a transaction problem. In practice, they are connected. A wallet that cannot organize balances across networks makes risk harder to evaluate; a tracker that ignores permissions and pending contract effects can make a clean-looking portfolio dangerously misleading. The useful comparison is not “wallet versus tracker,” but rather fragmented visibility versus an integrated process for observing, verifying, and authorizing activity.
Two Ways to Understand a DeFi Portfolio
A single-chain wallet offers a relatively narrow but often clearer view. It displays balances on one network, estimates transaction fees in that network’s native token, and presents contract interactions in a local context. For a user who only holds and swaps assets on one chain, this can be enough. The limitation is obvious: the apparent simplicity may come from excluding relevant information rather than reducing underlying complexity.
A multi-chain wallet takes the opposite approach. It groups addresses and positions across multiple networks so the user can see a broader economic picture. That is especially useful for DeFi users who supply liquidity on one chain, hold governance tokens on another, and bridge assets between them. The benefit is not merely convenience. It reduces what researchers in human-computer interaction would call a visibility problem: a risk is easier to miss when the facts needed to evaluate it are distributed across separate interfaces.
Yet a unified dashboard is not automatically a unified truth. Token prices may come from different market sources, liquidity may vary sharply between venues, and a position’s displayed value can change because of exchange rates, accrued rewards, debt, or impermanent loss. Some assets may be difficult to price at all. A portfolio total should therefore be treated as an estimate for orientation, not as a definitive statement of what could be withdrawn today.
This distinction matters for US users managing taxable activity as well as investment risk. A wallet view can help reconstruct where assets moved, but it is not necessarily a complete tax record. Cost basis, transfers between accounts, liquidity-provider positions, wrapped assets, and token rewards may require separate reconciliation. Portfolio tracking is a monitoring layer; it should not be confused with legal or tax advice, nor with a guaranteed accounting system.
Portfolio Tracking Is Also Attack-Surface Management
The most useful mental model is to treat a wallet as a control panel for permissions, not simply as a digital balance sheet. Your private key authorizes signatures, but a signed message can create ongoing consequences. An ERC-20 approval, for example, may allow a contract or spender to move specified tokens later. The immediate transaction may cost little and change no visible balance, while the permission itself expands the attack surface.
This is where smart contract simulation becomes valuable. Before signing, a wallet can attempt to execute a transaction in an emulated environment and show expected outcomes: tokens sent, tokens received, approvals created, fees charged, or assets that may be lost. The mechanism is similar to asking, “If this call were executed against the current state, what would the chain likely record?” That is more informative than displaying only a contract address and a gas estimate.
Simulation is not proof of safety. It depends on the quality and freshness of the simulated state, the accuracy of the wallet’s interpretation, and the behavior of the contracts involved. A transaction can depend on market prices, block timing, oracle updates, allowlists, or interactions that are difficult to model perfectly. A malicious contract may also present a harmless-looking path under one condition and behave differently under another. Simulation narrows uncertainty; it does not remove the need for judgment.
That limitation creates an important comparison between two user habits. One habit is address-centric: confirm that the destination looks familiar and sign quickly. The other is effect-centric: inspect what assets, permissions, and contract outcomes the transaction is expected to produce. Effect-centric review is generally the stronger discipline because copied addresses, familiar branding, and popular front ends do not guarantee that the requested call is appropriate.
Browser Wallet, Hardware Wallet, or Combined Workflow?
A browser-based wallet is usually the most convenient tool for interacting with decentralized applications. It can connect to exchanges, lending markets, staking interfaces, and bridges with relatively little friction. Its weakness is that convenience creates a larger opportunity for rushed approval. A user may click through several prompts without distinguishing a token transfer from a permission change.
A hardware wallet protects private-key operations by keeping key material in a separate device. That is a meaningful security boundary, particularly for long-term holdings. But it does not make a malicious transaction safe. If the user approves an unwanted contract call on the hardware device, the device may faithfully sign the mistake. Hardware protection addresses key exposure; it does not replace transaction comprehension.
The practical alternative is a layered workflow. Use a wallet with readable transaction analysis and simulation for daily interaction, keep high-value assets subject to stronger signing controls, and separate active DeFi funds from long-term holdings. This is not perfect compartmentalization—wallets can still share addresses, approvals, or operational habits—but it reduces the chance that one compromised application session exposes everything.
For users comparing interfaces, a tool such as rabby wallet is most useful when evaluated by this workflow rather than by feature count. Ask whether it helps you identify the chain, contract, assets leaving the wallet, assets arriving, newly granted permissions, and likely failure states before you sign. Security features have practical value only when they appear at the moment a decision is made and are understandable enough to change behavior.
What a Good Multi-Chain Review Looks Like
Before interacting with a DeFi application, first identify the network and the account. Network confusion is a mundane but consequential failure mode: the same token symbol can exist on several chains, while the application may silently switch networks or request a different account. Next, inspect the transaction’s economic effect. Do not stop at “swap.” Determine which asset is being spent, the minimum amount expected in return, the fee currency, and whether the transaction includes more than one call.
Then examine permissions separately from the immediate trade. An approval for an exact amount limits future movement more than an unlimited approval, although it may require another approval later and does not eliminate smart contract risk. Revoking an approval can also cost a network fee and does not reverse a transfer that already occurred. The security decision is therefore not simply “approve” or “never approve”; it is how much authority to grant, to which contract, for what purpose, and for how long.
Finally, compare the simulated result with your intention. If you intended to deposit one token and receive a receipt token, but the preview shows a transfer to an unfamiliar address, pause. If the result depends on a large price impact, a bridge message, or a new signature after the original approval, treat that as a separate decision. A transaction can be technically valid and still be economically irrational.
This process suggests a reusable heuristic: identity, effect, authority, reversibility. Identity asks who and which chain are involved. Effect asks what changes now. Authority asks what future actions are being permitted. Reversibility asks what can be undone if the application, market, or assumption is wrong. The fourth question is often neglected because blockchains are designed for final settlement, not convenient cancellation.
Where Multi-Chain Convenience Breaks Down
Cross-chain activity adds risks that a normal balance screen can hide. A bridge may lock assets on one chain and issue representations on another, creating dependence on contracts, validators, relayers, or message-passing systems. A portfolio tracker may display the resulting asset as if it were equivalent to the original, but equivalence depends on the bridge’s design and continued operation. “Same symbol” does not mean “same claim.”
There is also a measurement problem. DeFi positions are not always passive balances. Lending collateral, concentrated liquidity, vesting claims, synthetic assets, and leveraged positions can have obligations or liquidation thresholds that a simple total omits. A portfolio can rise in displayed dollar value while becoming more fragile because debt, concentration, or correlated collateral has increased.
That is why a higher portfolio total should not automatically be read as improved financial health. A better dashboard would ideally show exposure by chain, protocol, asset, counterparty or contract, and permission status, alongside uncertainty in pricing. Users can approximate this manually by separating liquid assets from locked positions, marking borrowed amounts, and reviewing old approvals. The goal is not perfect precision; it is avoiding false reassurance.
What to Watch as Wallets Become More Analytical
If wallets continue adding simulations, risk labels, and portfolio aggregation, the main competitive question may shift from how many networks they support to how well they explain uncertainty. A useful interface should distinguish confirmed on-chain facts from estimates, forecasts, and interpretations. It should also make stale data visible rather than presenting every number with the same visual confidence.
One plausible future direction is more intent-based interaction: the user states an objective, such as exchanging one asset within a maximum price impact, and the wallet compares possible routes. That could reduce technical friction, but it may also concentrate decision-making in routing systems and introduce new trust assumptions. The key evidence to watch is whether users can inspect and constrain the resulting calls, not merely whether the route is cheaper.
The durable lesson is simple but not simplistic. Portfolio tracking tells you where your exposure appears to be; transaction simulation helps estimate what a proposed action may do; neither substitutes for controlling permissions and separating risk. For DeFi users in the US and elsewhere, the strongest setup is not the interface with the most reassuring warnings. It is the workflow that makes the important questions difficult to skip.
Frequently Asked Questions
Can a multi-chain wallet replace a portfolio tracker?
It can replace a basic balance viewer for many users, but not necessarily a dedicated accounting or tax tool. Wallet data may not fully capture cost basis, complex DeFi positions, off-chain transactions, or assets held in other accounts. Treat the wallet as a control and monitoring layer, then reconcile important records separately.
Does transaction simulation guarantee that a contract is safe?
No. Simulation estimates the likely result under particular state and timing assumptions. It can reveal suspicious transfers, unexpected approvals, and mismatches with your intention, but it cannot prove that a contract is honest, solvent, well-governed, or safe under every future condition.
What is the most important thing to check before signing?
Check the full effect, not just the application name. Confirm the chain and account, assets leaving and arriving, contract address, permissions granted, fee, slippage, and whether the action can be reversed. If the result is unclear, the safest decision is to pause and investigate rather than rely on familiarity.